- Published on
How Phoenix-Area Contractors and Trades Can Fund Equipment and Growth Without Draining Cash Flow

If you run an HVAC, plumbing, electrical, roofing, landscaping, auto shop, or trucking business around Phoenix, a busy season can still strain cash flow. You may need trucks, tools, materials, or extra crew capacity before customers pay.
You can pre-qualify for financing in about two minutes with a soft credit pull that won’t affect your credit score. Call 800-203-2176 or email support@broadreachfinancial.com to talk through your options. Depending on the product and lender, some financing may close in as little as 48 hours.
Start with 0% business credit cards
For a planned, short-term business expense, stacking 0% business credit cards may be a useful first option. It means applying for multiple business cards as part of a deliberate funding plan, not firing off applications one after another. Some cards offer introductory periods of up to 18 months at 0%, depending on approval and the card’s terms.
That time can help you cover eligible business purchases while keeping cash available for payroll, fuel, and materials. But the promotional period ends. Make a realistic repayment plan before you apply, and check whether applications involve hard inquiries or personal guarantees. Read our guide to using 0% business card stacking carefully.
A FICO score of 650 or higher is generally recommended for our financing services. Eligibility and approvals depend on the applicant, lender, and product.
Match the funding to the need

Equipment leasing for trucks, tools, and machinery
When you need a service vehicle, diagnostic tools, a trailer, mower, or shop equipment, equipment leasing may help you acquire the asset without paying the full cost up front. Many leases include a $1 purchase option at the end, which may let you own the equipment after you finish paying. Check the agreement: terms, fees, purchase options, and eligibility vary.
A useful question to ask: will the equipment generate enough work or revenue to support its payments, including during slower periods?
Business line of credit for changing expenses
A business line of credit may fit recurring needs like materials, fuel, payroll, repairs, or bridging the time between a job and payment. You draw what you need, subject to the line's terms, rather than taking a lump sum. Depending on qualifications and lender, business lines may be available for up to $3 million.
Compare rates, fees, repayment terms, and draw frequency. Our guide explains business line-of-credit options.
Business term loan for a defined project
A term loan provides a lump sum with scheduled repayments. It may make sense for a planned expansion, a major equipment purchase, or a shop renovation when you know how much you need and can manage the payment over time.
A term loan may also help you pay down high-interest credit card balances. Lowering revolving balances can reduce credit utilization and may improve your credit profile, but it doesn’t guarantee improvement. Compare the loan’s total cost and payment with your current obligations, and avoid running the card balances back up. Keep payments current, review your credit reports for errors, and address any inaccuracies before applying.
Merchant cash advance for an urgent cash-flow gap
A merchant cash advance may provide faster access to funds based largely on business cash flow. It can be an option to explore when a time-sensitive expense can’t wait, but repayment may come frequently, and the overall cost can be high. Carefully review the total payback amount and payment schedule. Make sure the payments won’t squeeze the cash you need to keep crews and jobs moving.
Accounts receivable financing when invoices are outstanding
If you’re waiting on customer or commercial-account payments, accounts receivable financing may let you access funds tied to eligible outstanding invoices. It may help bridge the gap between finishing work and collecting payment. Advance amounts, fees, and whether the arrangement is with or without recourse vary, so understand the agreement before proceeding.
Plan around Phoenix’s work cycle

Phoenix businesses don’t all experience the same seasonal rhythm. Summer heat can drive HVAC calls while making outdoor work more difficult to schedule. Roofing and landscaping work can also shift with weather and job timing. Even when work is steady, invoice timing may not be.
Before taking on financing, map out expected expenses and incoming payments for a few months. Include payroll, fuel, materials, insurance, repairs, and any slower stretches. Then match the funding to the need: equipment financing for a long-lived asset, a line of credit for recurring working capital, or a term loan for a defined project.
Call 800-203-2176 or email support@broadreachfinancial.com. We’ll help you explore what may fit. Financing is available across all 50 states, not just Arizona. If you’re also looking at government-backed options, review the official SBA 7(a) loan program.
Talk it through before you commit
Steve’s business story began in 1984 with a car dealership. He later built Western All Tool Equipment Company and arranged tens of thousands of loans for customers. After selling his company, he bought a catamaran and crossed the Atlantic twice. He understands what it means to run a business, make a major decision, and keep moving when the numbers need a closer look.

Let Steve and Gale put their 30-plus years of business ownership and loan processing to work for you. Steve built and sold his own companies. Gale has processed loans for decades. They’ve sat on your side of the desk, and they’ll talk you through your options.
Start with a soft-pull pre-qualification in about two minutes. Call 800-203-2176 or email support@broadreachfinancial.com. Some financing may close in as little as 48 hours, depending on the product and lender.
Broad Reach Financial Services Inc. is a financing advisor, not a lender. We bring 30 years of experience helping businesses in all 50 states understand and compare financing options. Pre-qualification uses a soft credit pull that does not affect your credit score. Approval, rates, terms, eligibility, and funding times vary by lender and product. Call 800-203-2176 or email support@broadreachfinancial.com.
- Published on
SBA Loans vs. Business Term Loans: Which One Actually Fits Your Business?

You have a defined need. Maybe it’s equipment, expansion, a new location, commercial real estate, or working capital.
Now you’re deciding between an SBA loan and a business term loan.
Here’s the part almost nobody explains clearly: an SBA 7(a) loan is a term loan. The real comparison is an SBA-guaranteed term loan versus a conventional, non-SBA business term loan.
Broad Reach Financial Services is a funding advisor, not a lender. We compare options across commercial lenders, SBA resources, private investors, and other funding partners — 30 years in, all 50 states.
Let Steve and Gale put their 30-plus years of business ownership and loan processing to work for you. Steve built and sold his own companies. Gale has processed loans for decades.
They’ve sat on your side of the desk, and they’ll talk you through your options.
Pre-qualify with a soft credit pull in about two minutes — no damage to your credit rating, no obligation. Call or text 800-203-2176 or email support@broadreachfinancial.com.
The Main Difference: Who Stands Behind the Loan?
An SBA 7(a) loan is issued by a participating lender. The SBA provides the lender with a government guarantee, subject to program rules.
A conventional business term loan does not carry that SBA guarantee.
Both can provide a lump sum that you repay through scheduled payments over a defined term. Both can help fund a specific business goal.
The guarantee can affect the cost, repayment period, documentation, underwriting process, and eligibility requirements. That is what you are really comparing.
SBA Loan: Lower Cost, Longer Paperwork
SBA loans may offer longer repayment periods and favorable fixed terms for qualified businesses.
The SBA 7(a) program can support:
- Working capital
- Equipment and machinery
- Commercial real estate
- Business expansion
- Renovations
- Business acquisition
- Certain debt refinancing
SBA 504 financing is generally designed for major fixed assets such as commercial real estate, construction, and long-term equipment. It is not a general-purpose working capital product.
The trade-off is paperwork. Expect detailed underwriting, business and personal financial information, tax returns, debt schedules, ownership documents, collateral review, and an explanation of how the money will be used.
A personal guarantee is commonly required. Lenders may also require collateral, depending on the loan size and circumstances.
SBA backing does not mean automatic approval. You still need to show the business can repay the loan, the funds fit the program, and you meet the ownership and eligibility rules.
An SBA loan may fit you if:
- You have time for a more detailed process.
- You want to explore a longer repayment period.
- Your business has documented cash flow.
- Your ownership structure meets current SBA rules.
- You are funding a substantial, long-term project.
Some SBA processes may take longer than other financing options. That can be frustrating when a project is already moving. If you want to know whether the structure may fit before spending weeks gathering documents, call us at 800-203-2176 or email support@broadreachfinancial.com.

Business Term Loan: Faster, More Flexible
A business term loan provides a lump sum that you repay on a set schedule over a defined period.
The loan may come from a bank, online lender, commercial finance company, or another funding partner. Because it is not structured around an SBA guarantee, the lender may use a different approval process.
A business term loan may be used for:
- Equipment
- Renovations
- Expansion
- A new location
- Marketing and staffing
- Inventory
- Working capital
- A major business purchase
Compared with SBA financing, some term loans require less documentation and may close faster. Depending on the product and lender, some financing options may close in as little as 48 hours.
That speed can come with a higher cost or shorter repayment period. You may also see different collateral, personal guarantee, payment, and prepayment requirements.
A conventional term loan may fit you if:
- Your funding need is clearly defined.
- You need to move faster.
- Your request does not fit SBA program rules.
- Your ownership structure does not meet current SBA requirements.
- You have a simpler financing need than the SBA process warrants.
- You want to compare non-SBA options after a bank rejection.
If you need a fixed amount for a specific project, a term loan may be easier to understand than a revolving line of credit. For ongoing or unpredictable expenses, however, a business line of credit may be a better fit for working capital.
Want to compare a faster term loan with SBA financing? Call or text 800-203-2176. We’ll help you understand what may be available before you decide.

Important SBA Changes in 2026
Potentially higher combined SBA financing
Under a policy effective July 4, 2026, eligible borrowers may access up to $5 million through 7(a) and up to $5 million through 504, for a potential combined total of $10 million in SBA-backed financing, up from $5 million.
That $10 million is a combined maximum, not an automatic approval amount. Eligibility, repayment ability, collateral, project structure, lender requirements, and SBA rules still apply.
New ownership requirements
Beginning March 1, 2026, 7(a) and 504 applicants generally must be 100% owned, directly and indirectly, by U.S. citizens or U.S. nationals whose principal residence is in the United States, its territories, or possessions.
Under the updated policy, lawful permanent residents are no longer eligible to own an interest in an applicant Company. Review ownership carefully before assuming SBA financing is available.
The 7(a) Small Loan threshold changed
The 7(a) Small Loan threshold dropped from $500,000 to $350,000. This changes the underwriting treatment and documentation that may apply to larger requests.
The change does not mean every request above $350,000 is ineligible. It means the lender may process the request under a different SBA underwriting category.
Who Qualifies: The Rules That Trip People Up
The 2026 changes get the headlines, but these requirements trip people up in practice.
- For-profit, U.S.-based operating business. The business must operate in the United States, meet SBA size standards for its industry, and be organized in the U.S.
- Credit elsewhere. SBA financing is for businesses that can't get credit on reasonable terms from other sources. A bank "no" does not disqualify you — in some ways it is the point of the program.
- Personal guarantee. Every owner of 20 percent or more generally must sign an unconditional personal guarantee.
- Collateral is not always required. Loans of $50,000 or less do not require collateral. Above that, the lender follows its own policies for similarly sized non-SBA loans.
- Equity injection for startups and acquisitions. Startups and business acquisitions generally require a 10 percent equity injection.
- No SBA minimum credit score. The SBA does not set one. But most SBA lenders set their own floor, often in the 640 to 680 FICO range, close to the 650 FICO we generally recommend.
Rules and lender policies change, and each lender applies its own standards on top of the SBA's. Call or text 800-203-2176 or email support@broadreachfinancial.com, and we will tell you where you stand before you spend weeks gathering documents.
SBA Loans vs. Business Term Loans: At a Glance
- Cost structure: SBA loans may offer more favorable pricing for qualified borrowers. Conventional term loans may cost more, especially when they provide faster or more flexible approval.
- Repayment shape: Both are generally lump-sum loans repaid through scheduled payments. SBA loans may offer longer terms, depending on the program and how the funds are used.
- Funding speed: Conventional term loans may close faster. Some options may close in as little as 48 hours, depending on the lender and product. SBA financing often takes longer.
- Documentation: SBA loans usually require more detailed financial, ownership, tax, and collateral documentation. Non-SBA term loans may require less, but requirements vary.
- Collateral: Either option may require collateral or a personal guarantee. The exact requirement depends on the lender, loan size, and business profile.
- Credit requirements: Financing services generally recommend applicants with a FICO score of 650 or higher. That is a recommendation, not a guarantee. Some cash-flow-based options may exist for owners who do not meet a FICO-based standard.
- Eligibility rules: SBA loans must follow SBA program rules, including current ownership requirements. Conventional term loans follow the selected lender’s rules.
- Best fit: SBA financing may fit a larger, long-term project when you have time. A business term loan may fit a defined need when speed or flexibility matters more.
Which One Fits Your Business?
Choose an SBA loan if you have time, want to explore a longer repayment period and potentially lower cost, have documented repayment ability, and your ownership structure meets current SBA rules.
Choose a conventional business term loan if you need to move faster, want a simpler process, don't meet current SBA citizenship or ownership requirements, or have a defined project that doesn't justify extensive SBA documentation.
And if a bank already said no, that may not be the end of the road. A lender’s decision reflects its own rules. After a bank rejection, you can explore other small business funding options

Let’s Compare Your Options
SBA loans and business term loans can both help fund a defined business need. The better choice depends on your timing, cash flow, ownership, documentation, credit profile, collateral, and the project itself.
Call or text 800-203-2176 or email support@broadreachfinancial.com. The soft-pull pre-qualification takes about two minutes, doesn't affect your credit rating, and has no obligation. We’ll help you understand what you may qualify for and connect you with potential funding sources.
Other lenders fit you into their program. We fit the program to you.
Disclaimer: Broad Reach Financial Services Inc. is not a lender. We provide education and financing guidance and connect clients with commercial lenders, SBA resources, private investors, and other funding sources. Approval, rates, terms, fees, eligibility, collateral requirements, and funding times vary by lender, product, applicant, and business circumstances. No outcome is guaranteed. This article provides general educational information and is not legal, tax, or financial advice.
- Published on
Funding Disneyland
Updates| American Dream & Funding| Business Funding Strategies| The Funding Machine| Entrepreneurial Mindset| Entrepreneurship| Business Growth & Scaling| Business & Personal Credit
September 09, 2026•10 min read
The $17 Million Dream!
The Playground of Capital
You could teach a hundred business classes on Walt Disney. The guy is a walking case study on taking massive animation risks, building intellectual property flywheels, and generally bending the world to his will. But we aren't getting into all of that right now (maybe another day!). Today, we're going to Disneyland! Woo-hoooo!
Let's set the scene. Walt wanted to build a literal, functioning municipality from scratch. We're talking about an unprecedented $17 million physical world. Here's the problem. Banks don't fund crazy. Back then, traditional lenders only handed over cash for proven, boring,g and static business models. Walt pitched a massive castle and a fake jungle — and the bankers laughed him right out the door.
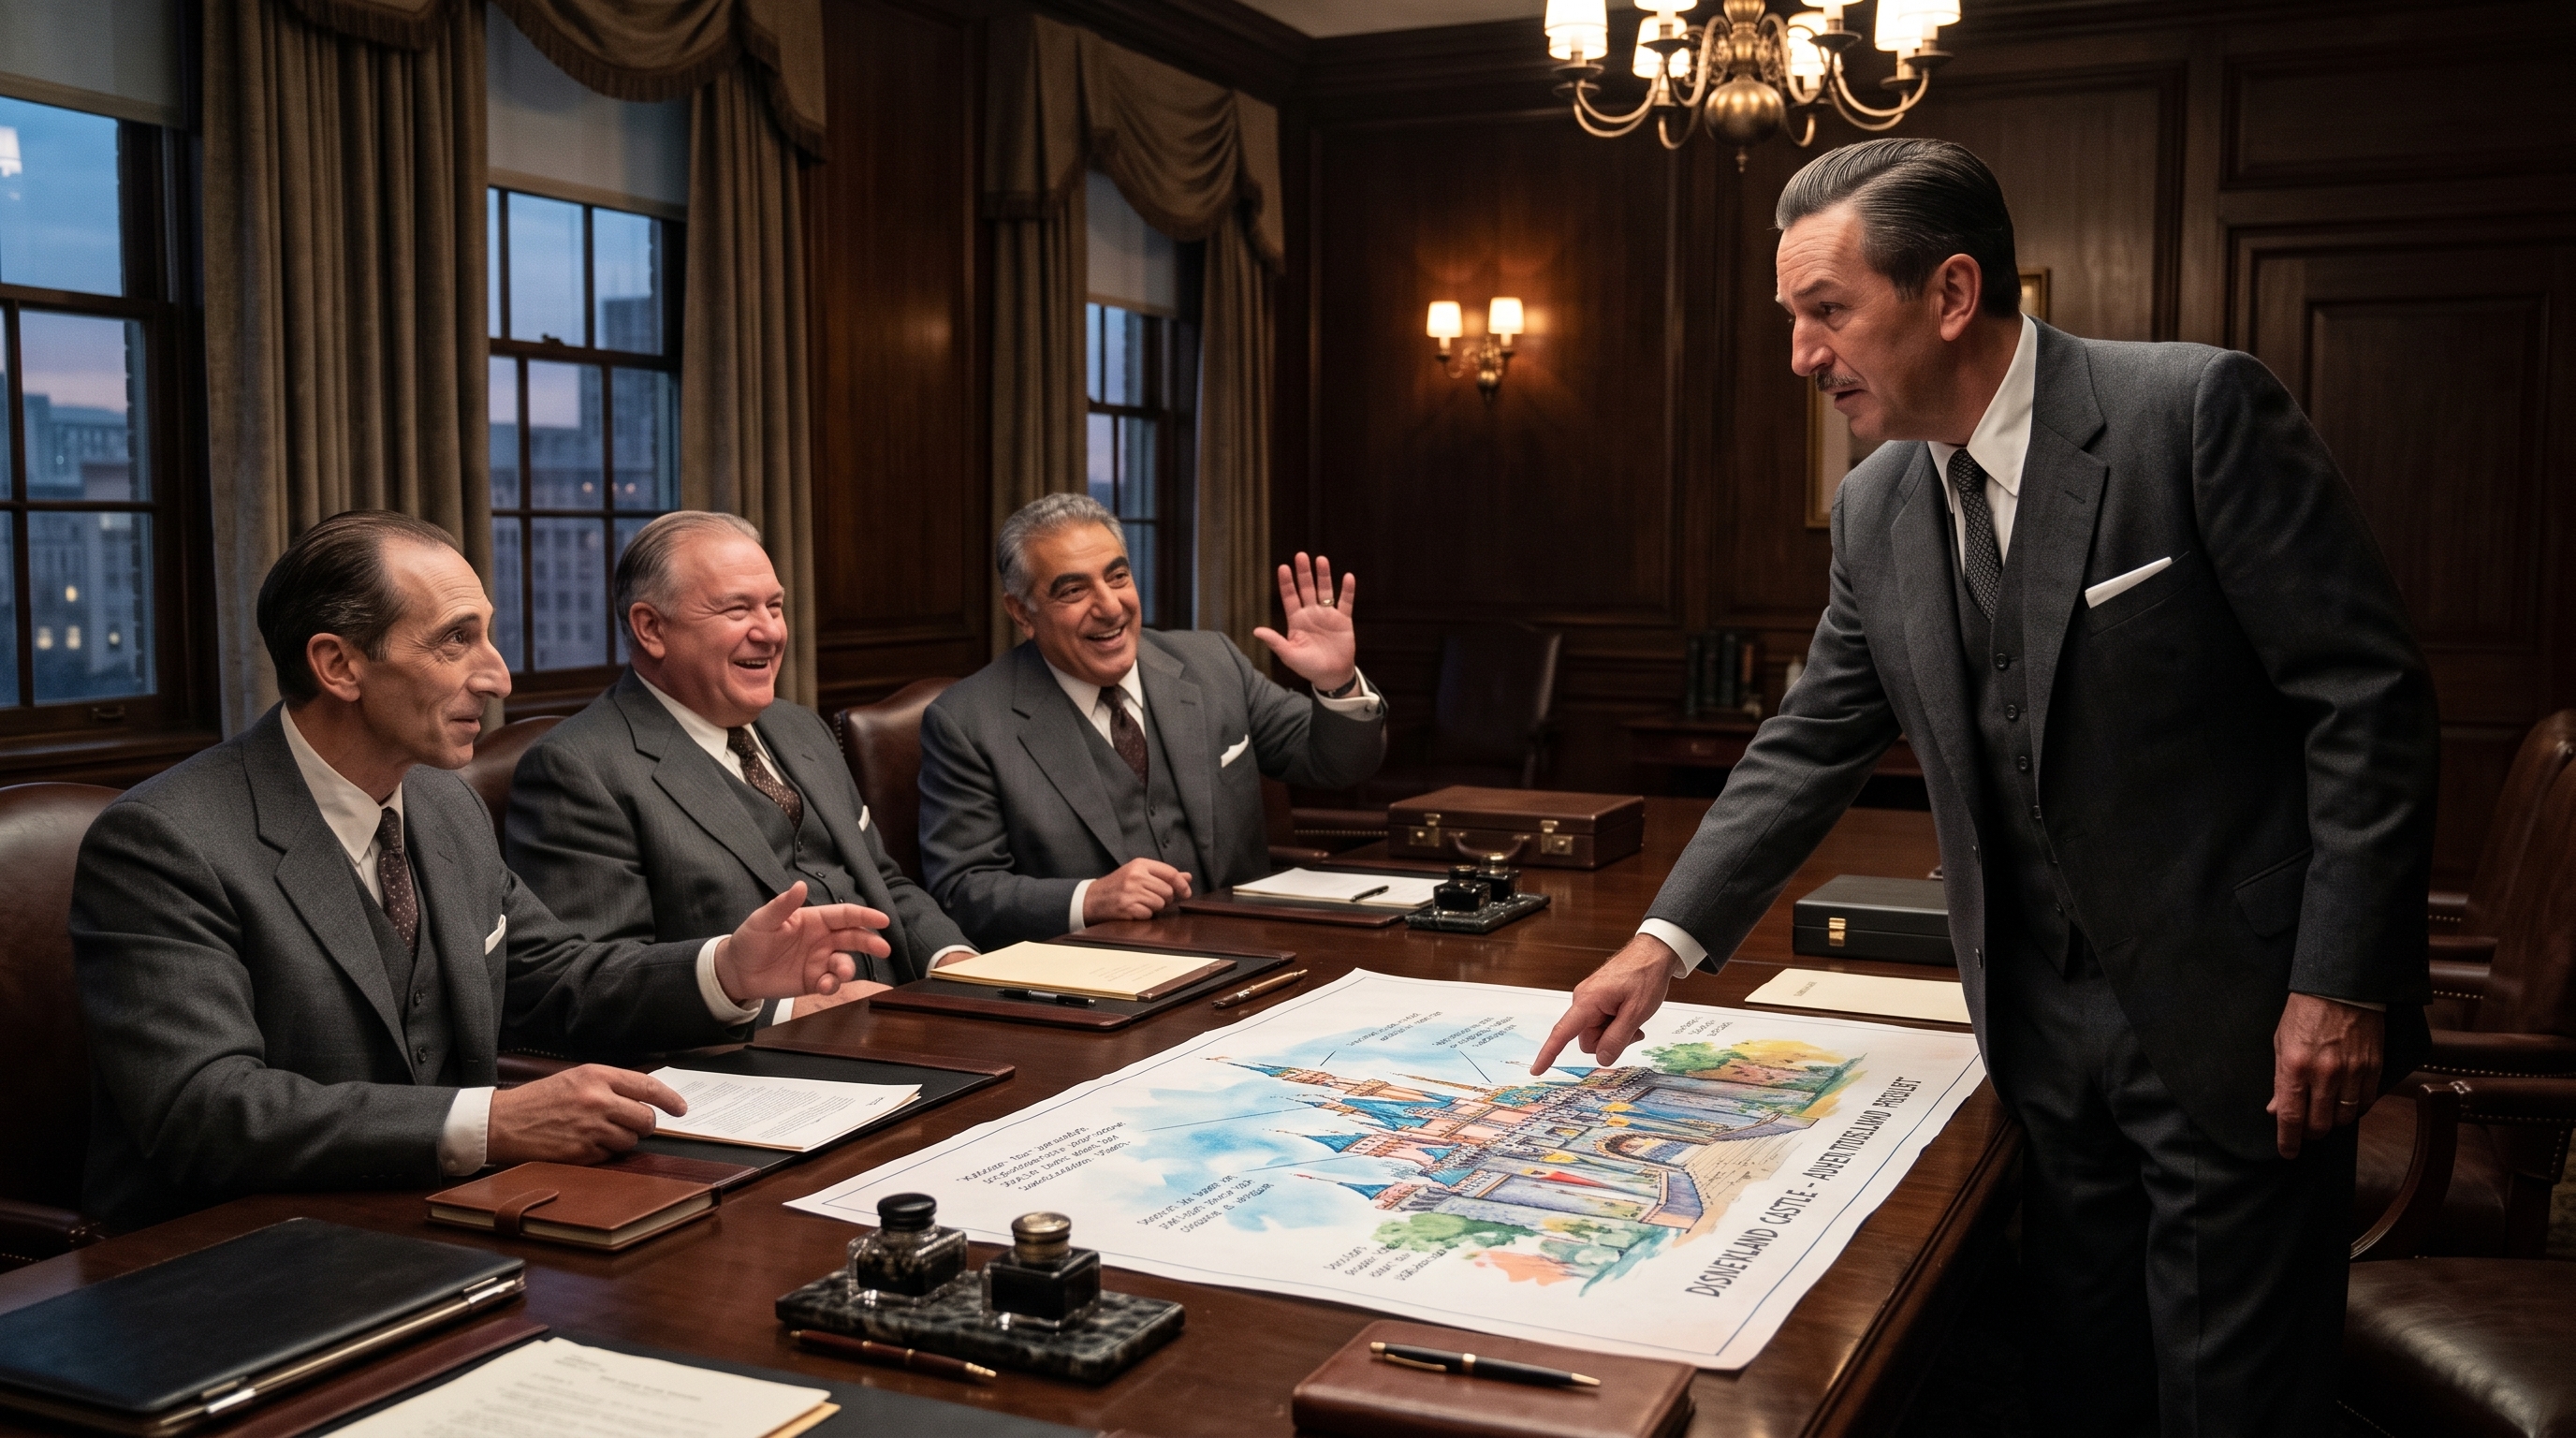 If you've ever had a lender reject your vision, you know exactly how much that stings (I've been laughed out of a few rooms myself, though usually for much worse ideas).
But it's totally ok when the traditional suits say no. When traditional banking shuts its doors, you don't pack up and quit. You hold yourself accountable to the dream, and you get to work. Successful founders assemble their capital from non-traditional assets, strategic partnerships,s and future revenue.
The $10,000 Leash & The Life Insurance Pivot
The early 1950s were brutal for Walt Disney Productions. The studio was dragging around massive debt because movies like "Pinocchio" and "Fantasia" — despite being classics today — actually lost a ton of money at first.
For the executives running the show, there was absolutely zero room for speculation.
Then you had the cultural stigma. Back then, financiers looked at amusement parks and saw dirty, low-margin carnival operations. They didn't see a magical family destination. They saw a terrible investment. Enter Roy Disney. He was the money guy trying to keep the studio alive. To humor his brother without bankrupting the company, Roy put an incredibly tight leash on the project, officially capping theme park research at an impossibly low $10,000.
(If you've ever had a partner tell you to launch a massive business with pocket change, you feel Walt's pain right here).
Walt knew corporate bureaucracy would suffocate his dream, so he made a brilliant structural pivot. In December 1952, he formed WED Enterprises as a private company. This completely firewalled the public studio and shielded the nervous stockholders from liability. More importantly, it gave Walt the unrestricted design freedom he desperately needed.
With his creative engine isolated, Walt ignored Roy's tiny budget. He hired a research firm for $25,000 to run demographic algorithms and do the "roller-coaster math". His data pinpointed the epicenter of future growth, and they locked down a 160-acre parcel of Anaheim orange groves for just $4,500 an acre.
When it came time to fund it, the initial pitch projected $5 million. It was deliberately low to placate the conservative debt markets. The banks still didn't bite. Bank of America and Bankers Trust took one look and completely balked. Wall Street had a strict rule. They believed amusement parks without roller coasters were mathematically guaranteed to fail. The risk was so wild that his own brother Roy started calling the project "Walt’s Folly".
With the traditional front door locked, Walt kicked down the back door.
He started liquidating his personal wealth and even sold off his vacation home in Palm Springs. But the real genius was how he leveraged his life insurance. Walt and Lillian had whole life insurance policies. If they borrowed directly from the insurers, they'd pay a standard 6% interest rate. Walt didn't do that. Instead, he took the policies to Commerce Trust in Kansas City. He used the cash value as collateral to secure a $60,000 loan at a tiny 2% interest rate.
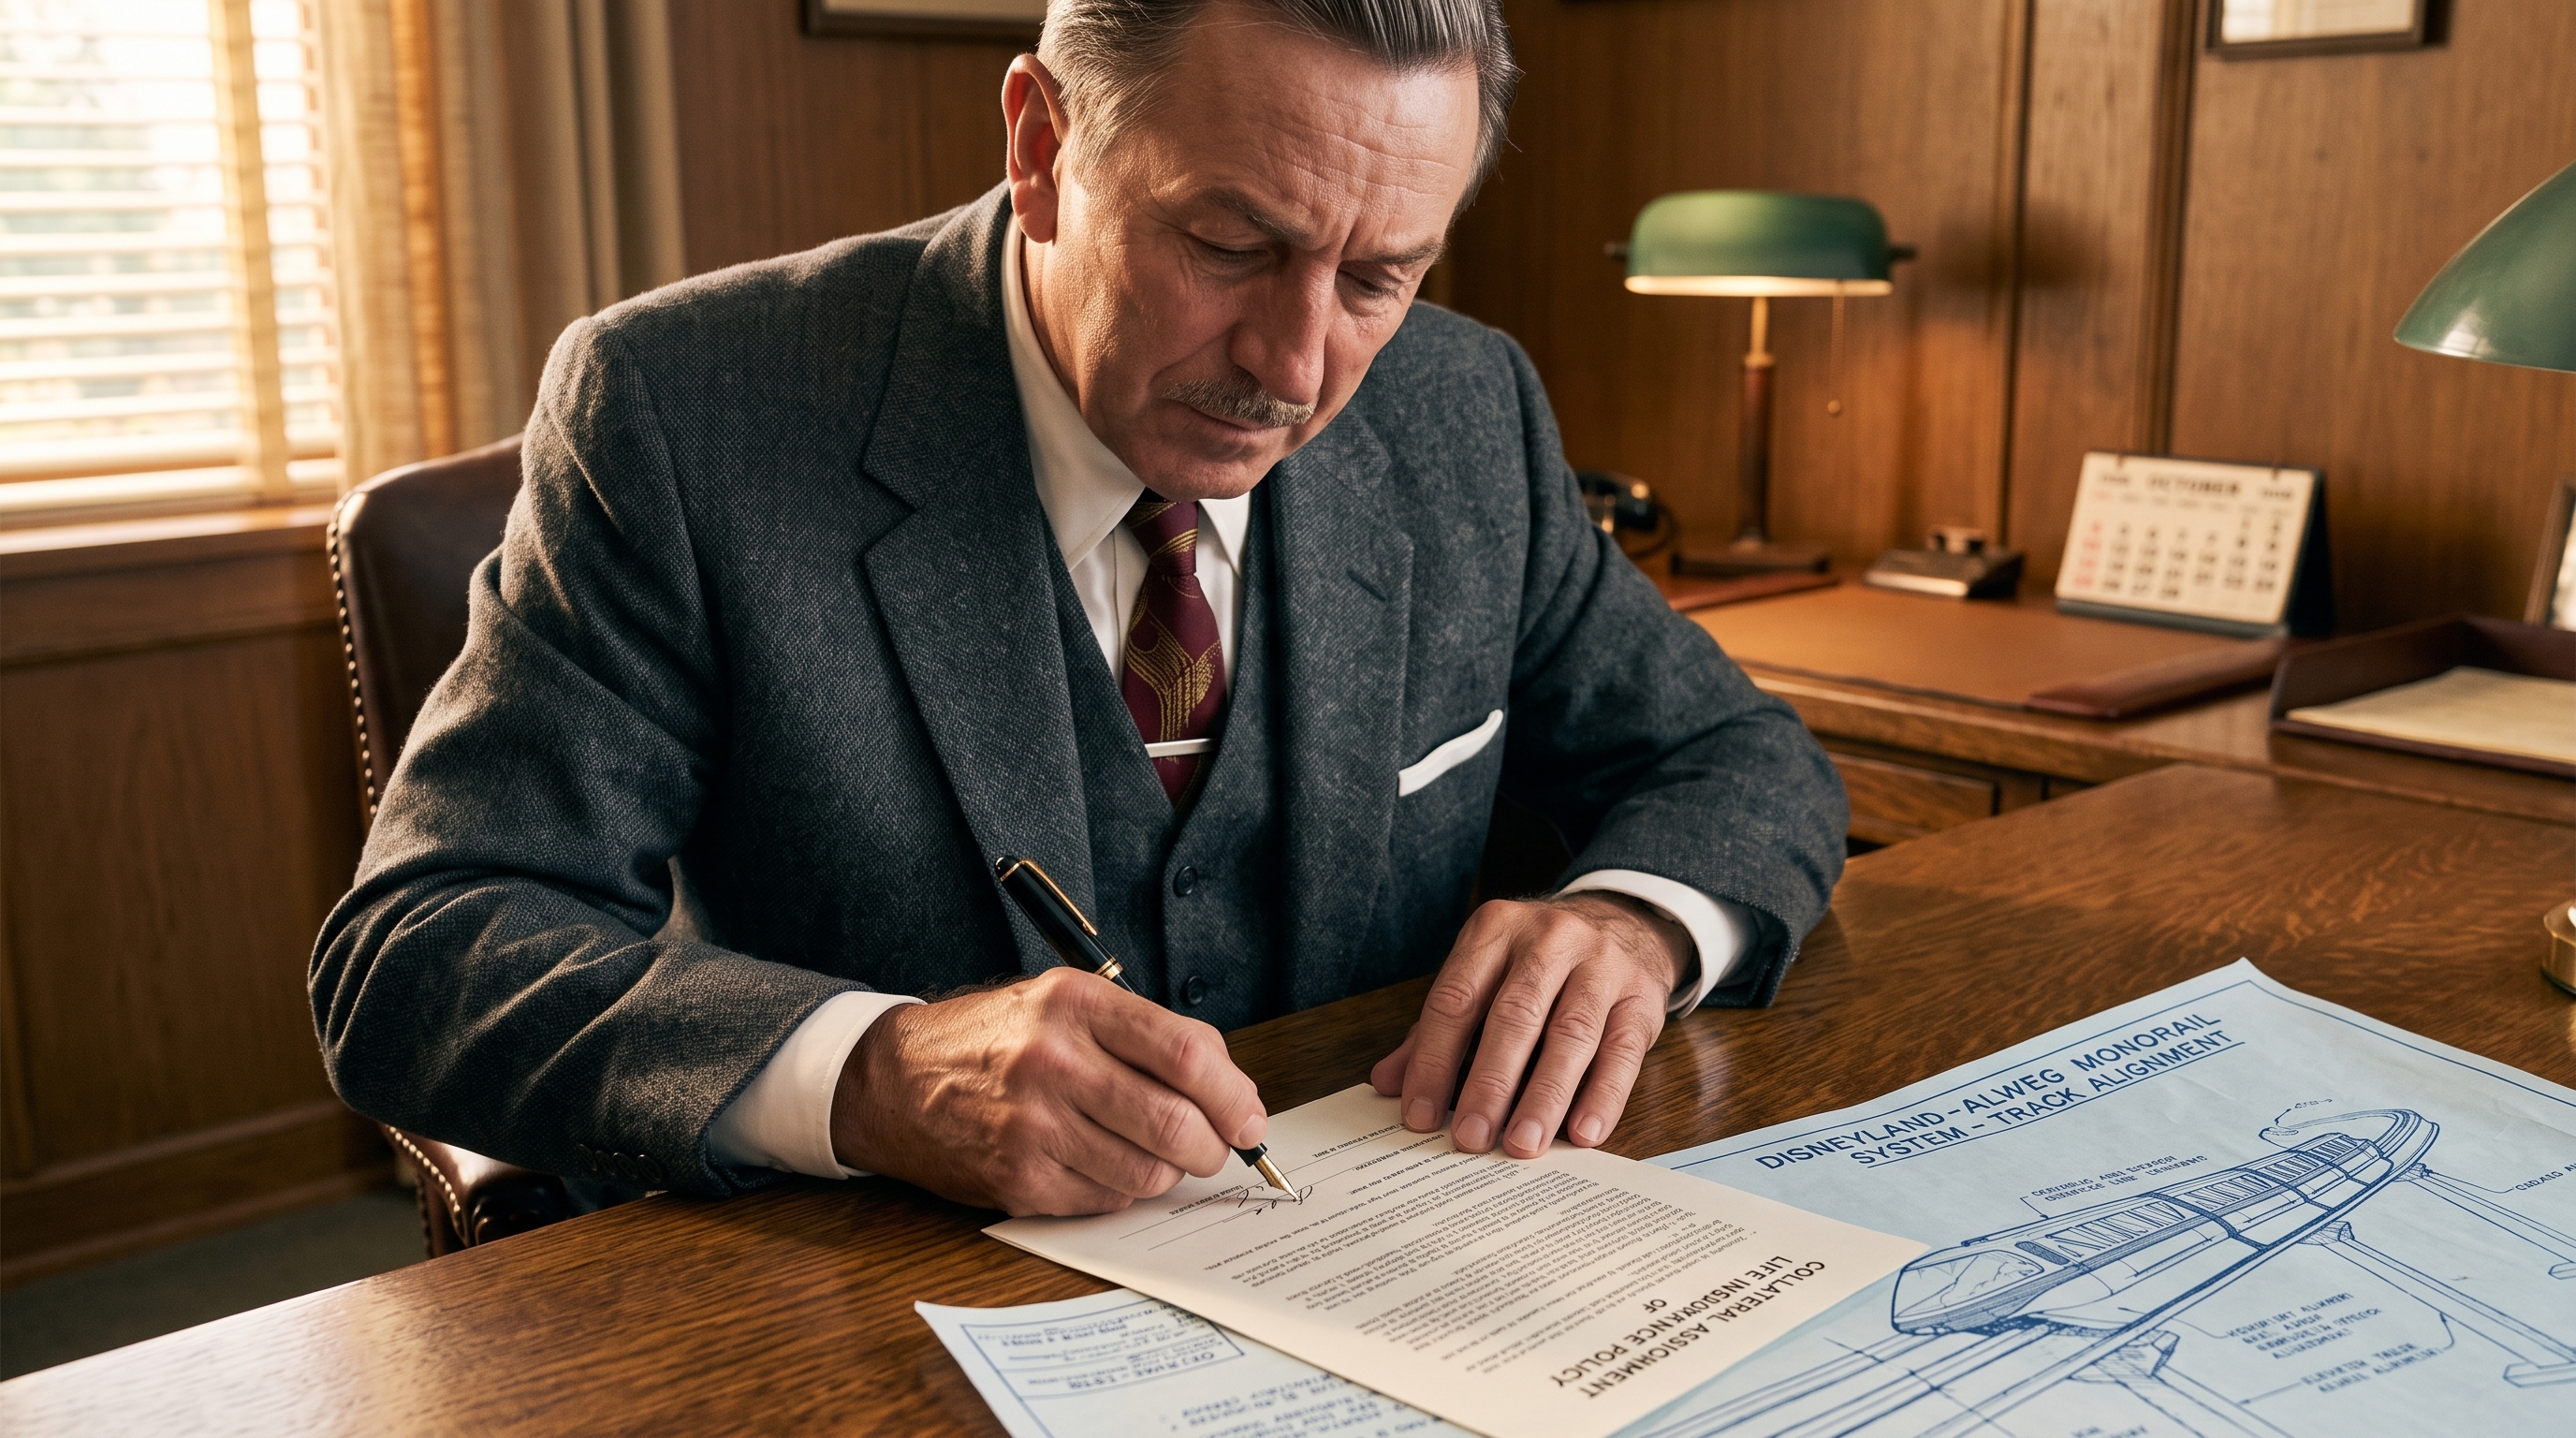 (That is exactly how you bypass the system when the rules don't work for you).
Between the house and the policies, Walt injected $250,000 of his own cash to grab a 16.55% stake in the newly formed Disneyland, Inc.
Dropping that much personal cash on an unproven theme park is terrifying. Lillian was absolutely furious. To pacify her and keep the peace at home, Walt cut a deal, granting her a 15% return on all park merchandise bearing his name.
But Walt also protected himself. He hedged his bets perfectly through WED Enterprises. He retained direct, private ownership of the park's railroad and monorail systems. Plus, he locked in a 10% royalty on the licensing of his own name. He built a private cash engine that paid him out regardless of what happened to the overall corporate margins.
The Network Standoff
Walt needed heavyweight capital to actually build this thing. So, he pitched the giant broadcast networks.
They completely blew him off.
William S. Paley at CBS dismissed the whole project as "just another Coney Island" and literally stood the Disney brothers up at a crucial meeting.
Next, they went to NBC. David Sarnoff desperately wanted Walt's TV content, but flat-out refused to touch the real estate. He famously barked, "I want your television show, but why the hell do we have to take that damned amusement park?"
(When the guys at the top tell you no, it's usually because they lack the vision to see what you're actually building).
Walt didn't quit. He just pivoted to the underdog and approached Leonard Goldenson at ABC.
Back then, ABC was dying in dead last place. Industry insiders literally called it the "Almost Broadcasting Company". They were absolutely desperate for a hit, and Walt knew exactly how to leverage their pain.
On April 2, 1954, they locked in a massive landmark agreement.
ABC handed over $500,000 in cash for a 34.485% equity stake in the park. More importantly, they guaranteed $4.5 million in commercial bank loans. That guarantee was the magic bullet that finally forced the traditional banks to open their wallets.
But ABC didn't do it out of the goodness of their hearts. They demanded a 10-year exclusive monopoly on all food and beverage concession profits inside the park.
When the dust settled, the Disneyland, Inc. pie was sliced four ways. Walt Disney Productions held 34.48%, ABC grabbed 34.485%, Walt personally held 16.55%, and Western Publishing filled the gap with 13.80%.
Here is the absolute masterstroke. Walt signed a 7-year TV contract with ABC, paying him $5 million a year.
He successfully got the network to pay him millions to run a self-liquidating, hour-long weekly advertisement for his own theme park.
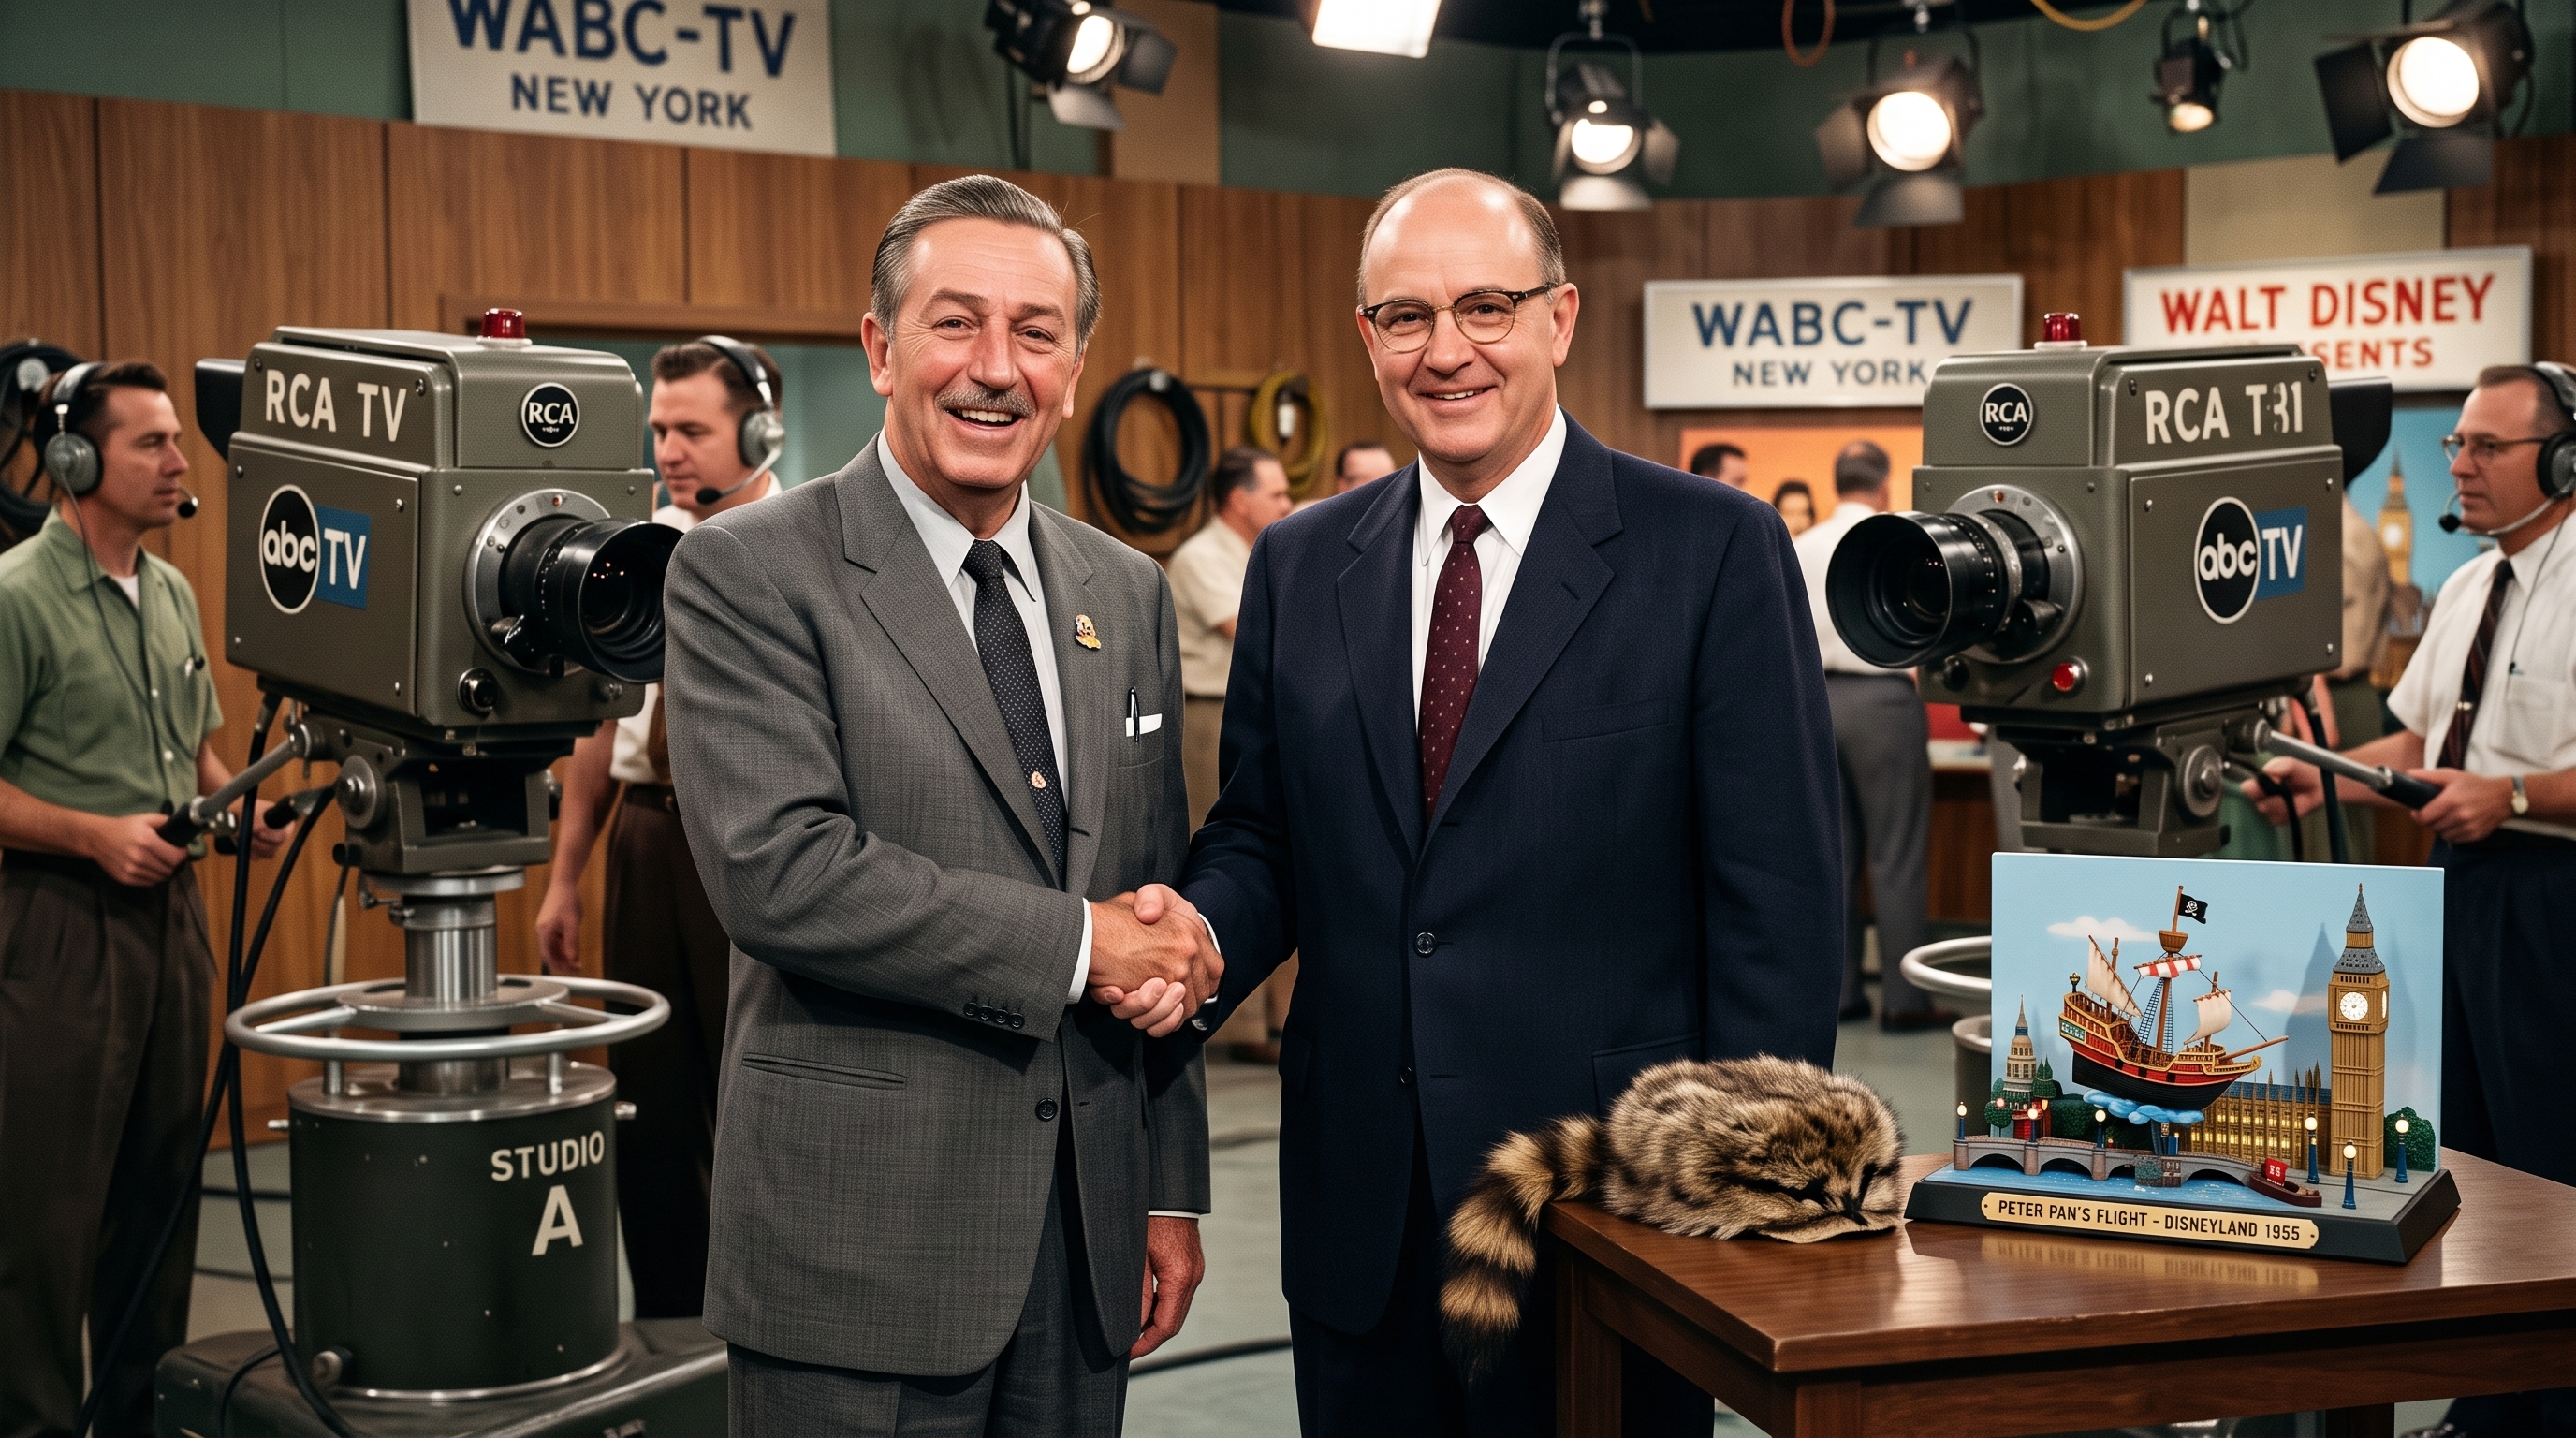 The impact was insane. The show's Davy Crockett episodes sparked a nationwide craze, generating $300 million in merchandise sales in 1955 alone. That massive wave of indirect cash pumped right back into the Disney ecosystem, keeping the entire dream alive.
The $17 Million Reality Check & Corporate Crowdsourcing
You know that original $5 million pitch? It fell apart almost immediately.
The main contractor took one look at the wild sketches on the wall and bumped the estimate up to $9 million. But because Walt constantly changed his mind and demanded on-the-fly revisions, that number completely exploded. By opening day, the actual cost hit a staggering $17 million.
(If you've ever tried to renovate a kitchen, you know exactly how fast a budget can blow up; now imagine doing it with a fake jungle and a massive castle).
Building a fake world in the real world is brutal. They had a non-negotiable 365-day construction schedule. That meant throwing over 800 workers across 60 different subcontractors at the dirt every single day. Add in 29 competing labor unions fighting over jurisdiction, and you have a recipe for pure chaos.
To hit that opening day deadline, Walt had to bleed cash. Workers were pulling round-the-clock shifts and hitting "golden time" premium pay. Some of these guys were taking home nearly $1,000 a week in 1955.
Then a national plumbers' strike hit right before the gates opened. Walt was faced with a brutal ultimatum. He had to choose between finishing the bathrooms or finishing the drinking fountains. Facing a massive heatwave, he pragmatically chose the bathrooms.
All of this threw the back office into a total panic. The accounts payable team was shoved into a cramped, dark office they dubbed "The Snake Pit".
The bookkeepers were literally drowning. They sat there trying to process three massive tubs filled with $17 million in unpaid vendor invoices. The initial seed money was completely gone — and they were staring down a massive financial cliff.
 Walt didn't have the cash to cross the finish line. To bridge that massive capital gap, he tapped into a brilliant commercial real estate loophole: tenant-improvement leases.
His team went out and aggressively pitched major American brands to open shop inside the park. Russel Tippett and George Whitney hit the pavement and locked down 33 original corporate sponsors.
The economics on these deals were absolutely wild. If a company wanted an in-line facility, they paid $40,000 a year. If they wanted a custom pavilion, it cost them $100,000 a year.
But here's the real genius — the corporate tenants also had to foot 80 to 90 percent of their own construction costs.
The biggest brands in the world happily opened their wallets. Carnation bought a dairy monopoly inside the park. Eastman Kodak, TWA, and Pepsi-Cola all funded their own footprints.
Bank of America even built a fully functioning branch right on Main Street. More importantly, they stepped in to float the bleeding company by providing a critical $9 million participation credit facility alongside Bankers Trust.
(That is exactly how you leverage relationships to keep the lights on).
Walt effectively crowdsourced the final construction costs. He retained total ownership of the underlying land, but he used massive corporate balance sheets to actually finance the physical buildout of his dream.
 Black Sunday to Black Ink
Disneyland officially opened on July 17, 1955. Walt literally called it "Black Sunday".
The asphalt was so fresh and soft that women's high heels sank right into the street. They planned for 15,000 guests, but counterfeit tickets flooded the gates and 33,000 people showed up. Rides broke down, and the restaurants completely ran out of food.
(If you've ever had a product launch go sideways — at least you didn't trap your clients in melting pavement).
Despite the operational nightmare, the financial engine was an absolute monster. They charged $1.00 at the gate to walk in. Once inside, you paid cash for every single ride.
By October 1955, they got smart and rolled out the famous Ticket Books for $2.25. This forced families to prepay for attractions in bulk, dumping a massive wave of upfront cash right onto the balance sheet.
 The traffic was insane. They hit 1 million guests in just seven weeks. By the end of year one, 3.6 million people had visited. The park grossed $11 million and cleared over $1 million in pure net profit.
Walt didn't want to share his cash cow forever. In 1960, Disney bought out ABC's 34.485% equity stake for $7.5 million. He drained $2 million in cash from the park and financed the remaining $5.5 million with five-year notes. ABC walked away with a 15x cash return, and Walt reclaimed total control.
(As a hilarious final flex, Disney got so big they eventually bought the entire ABC network decades later for $19 billion.)
The Modern Funding Playbook
Fast forward to today. The brutal truth is that traditional bank underwriting hasn't changed much since the 1950s. They are still entirely backward-looking. They rely on static scorecards and rigid templates to tell them if a deal is safe.
If your business doesn't fit perfectly into their little box, they hit reject — and that's totally ok.
(I've stared down my fair share of those rejection letters, and they never get any less annoying).
But here's the secret you need to understand. When a standard commercial lender rejects a perfectly viable enterprise, the business isn't dead. The financing structure is simply incomplete.
Stop begging legacy bank underwriters for permission to grow. You have to build your own capital stack. Today, you do that by combining 0% introductory credit options, smart asset leverage, and alternative credit structures. You build automated digital funnels to pre-screen deals and find the backdoor when the front door is locked.
You don't need a guy in a suit to validate your vision. You need the right alternative financial tools and the guts to actually use them. Hold yourself accountable, respect your own hustle, and fund your dream.